Key Takeaways
- Monthly fees usually bundle rent, utilities, meals, and housekeeping into one payment
- Start your budget by listing income, savings, property, and monthly bills
- Compare current household costs to the community’s monthly fee before deciding
- Veterans benefits, long-term care insurance, and state programs may help
- Selling or renting a home can free up funds to support your move-in budget
- Read the contract closely and ask how fees change over time
How to Plan Financially for Assisted Living
You’ve probably sat at the kitchen table with a notepad, trying to figure out whether a move to senior living adds up. The numbers feel big, and the brochures don’t always explain what they mean.
That uncertainty is the hardest part, not the math itself. Our team at Longevity Living of Godfrey hears this from families every week.
Once you know what the monthly fee covers, what bills disappear, and what benefits you may qualify for, planning for assisted living becomes a clear set of steps instead of a guessing game.
What Assisted Living Costs Typically Cover
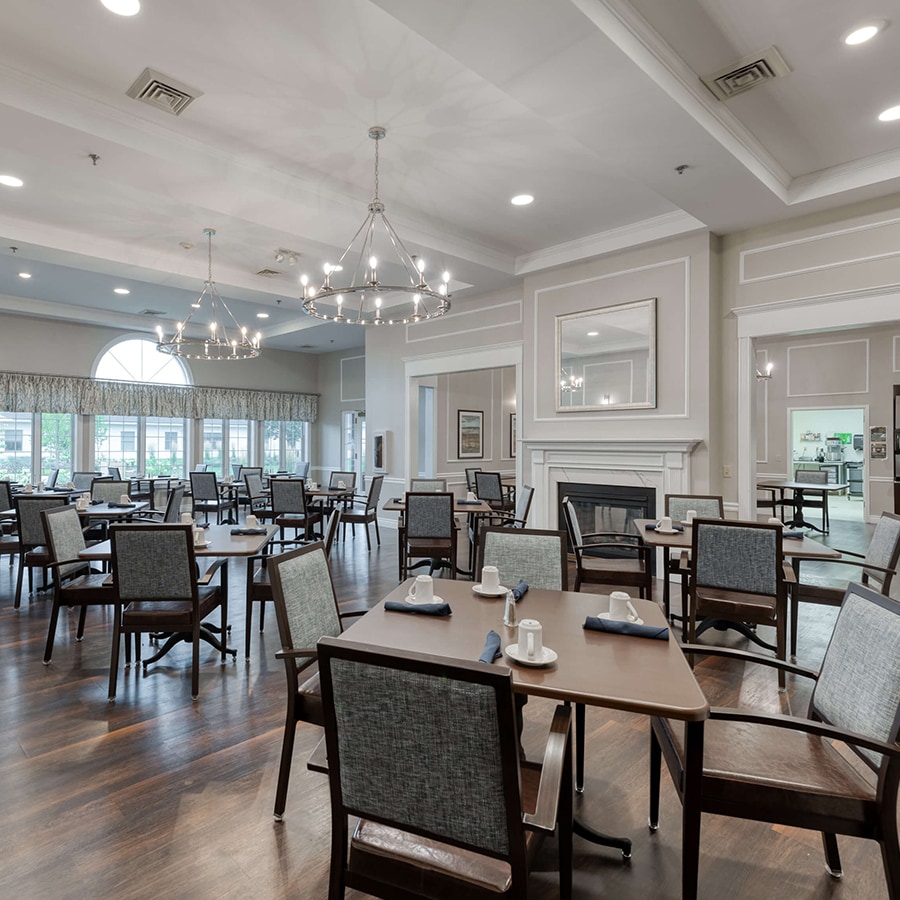
Most communities charge one monthly fee that bundles several things together. That usually includes rent, utilities, chef-prepared meals, and housekeeping. Instead of 8 separate bills arriving each month, you get a single statement.
The fee also typically covers daily activities and personal care help, like bathing, dressing, and medication reminders. Added services, such as extra transportation or specialized care, may carry separate fees. Ask exactly where that line sits.
Why Prices Vary by Community
Communities 30 miles apart can quote very different numbers. Location plays a role, along with the level of care a resident needs and the amenities offered on site.
The simplest way to compare apples to apples is to request a sample invoice and a written fee schedule. A real invoice shows you how charges appear in practice, not just in a sales conversation.
Tip 1. Review Your Current Financial Picture
Before you tour anywhere, put everything on one page. It takes an afternoon and can save months of second-guessing.
- Savings accounts, CDs, and investment balances
- Monthly income from Social Security, pensions, or annuities
- Property, vehicles, and other assets that could be sold
- Monthly expenses and debts, such as a mortgage or car loan
Seeing the full picture helps you answer the real question. Not whether this is affordable today, but how many years it can comfortably cover.
Tip 2. Build a Budget That Looks Ahead
Line up your current household bills next to the community’s monthly fee. Families are often surprised by how close the 2 columns sit once you count every cost.
Then plan for change. Care needs can shift over the years, and fees may shift with them. Setting aside a cushion for surprise costs, like a new hearing aid or a dental bill, helps keep small expenses from becoming stressful.
Reviewing long-term care services ahead of time helps you picture what’s next.
Household Bills You May No Longer Pay
- Electric, gas, water, and trash service
- Groceries and dining out
- Lawn care, snow removal, and pest control
- Home repairs, appliance replacement, and property taxes
- Homeowners insurance
Tip 3. Explore Benefits and Assistance Options
Many families leave money on the table simply because no one told them to ask. A few programs are worth checking into:
- VA Aid and Attendance, available to some veterans and surviving spouses
- Long-term care insurance, if a policy is already in place
- Medicaid waiver programs, which vary by state
If a long-term care policy exists, pull the actual documents. Coverage amounts, waiting periods, and daily benefit limits vary widely from one policy to the next. It also helps to know Medicare doesn’t cover assisted living costs.
How Most Families Cover Costs
In practice, funding usually comes from a mix of sources rather than one. Savings, Social Security, pension income, and contributions from adult children often work together.
Some care-related expenses may also qualify as tax deductions. Ask a tax professional before you file next spring.
Tip 4. Make the Most of Home and Assets
The family home is often the largest piece of the puzzle. Selling it can free up funds, or renting it out can create steady monthly income. Some families also explore financing options for senior living while a sale is pending.
Timing matters. A conversation with a local real estate agent can tell you whether waiting a season makes sense for your area.
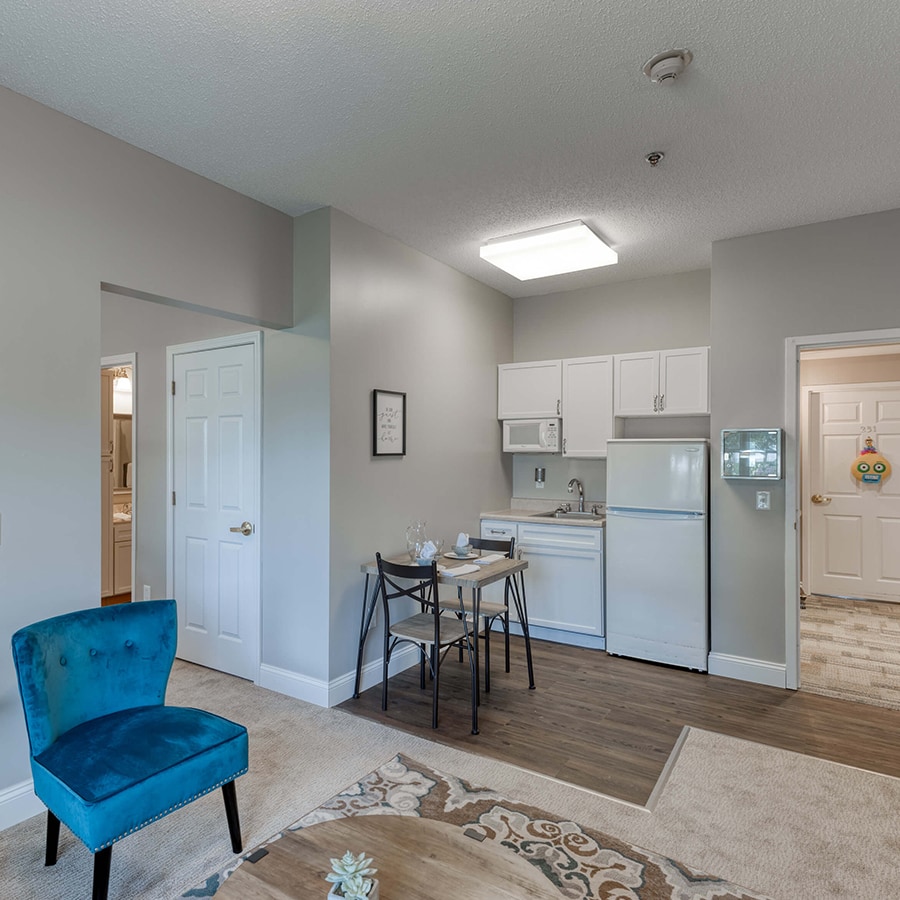
Downsizing also has quiet financial upside. An extra vehicle, a workshop full of tools, or furniture that won’t fit the new community apartment can all turn into cash that supports the move.
Tip 5. Ask Questions Before You Sign
Read the agreement slowly, and take it home first. Review the contract type, any required deposit, and the refund policy if your plans change. Many communities use tiered pricing, where the fee reflects the level of care provided.
Knowing who typically lives in assisted living can help you match the right tier.
A financial advisor or an attorney who works with families on these decisions can review the paperwork with you. An hour of their time often pays for itself.
Questions Worth Raising with the Team
- What’s included in the monthly fee, and what carries an added charge?
- How and when do fees change as care needs change?
- How much notice do residents receive before a rate increase?
- What happens to the deposit if plans shift?
Next Steps Toward a Clear and Calm Move
Know the costs, build a budget that looks ahead, explore every benefit, and ask plenty of questions. Start these conversations with your family early, while you still have time to weigh options without pressure.
Comparing assisted living and independent living is a helpful place to begin.
Our team at Longevity Living of Godfrey is happy to walk through pricing line by line and answer any questions. Reach out to schedule a tour and see what daily life here looks like.